Newton Polynomial Interpolation
Newton interpolation represents the same unique polynomial obtained by Lagrange interpolation, but in a form that is easier to build incrementally.
For distinct nodes
$$ x_0,x_1,\ldots,x_n, $$
the Newton polynomial is
$$ P_n(x) = a_0 + a_1(x - x_0) + a_2(x - x_0)(x - x_1) + \cdots + a_n\prod_{j=0}^{n-1}(x - x_j). $$
The coefficients $a_k$ are divided differences.
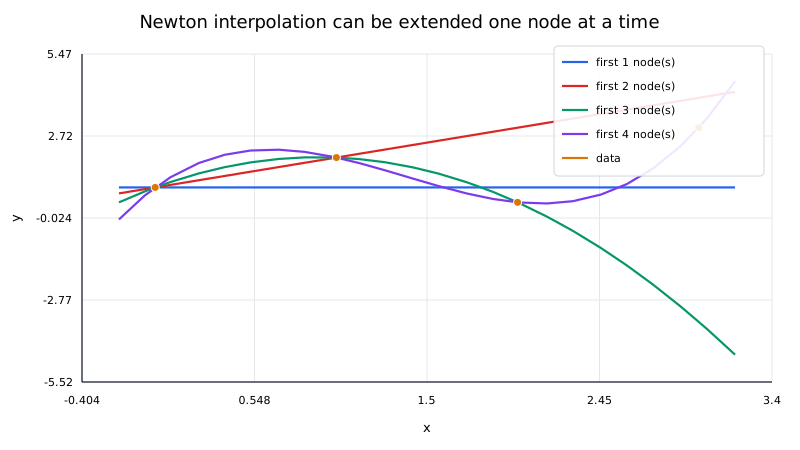
The key advantage is structural: when a new point is added, the previously computed terms do not need to be changed. One new coefficient and one new product term are appended.
Divided differences
The zeroth-order divided differences are simply the data values:
$$ f[x_i] = y_i. $$
First-order divided differences are secant slopes:
$$ f[x_i,x_{i+1}] = \frac{f[x_{i+1}]-f[x_i]}{x_{i+1}-x_i}. $$
Higher-order divided differences are defined recursively:
$$ f[x_i,\ldots,x_{i+k}] = \frac{ f[x_{i+1},\ldots,x_{i+k}] - f[x_i,\ldots,x_{i+k-1}] }{ x_{i+k}-x_i }. $$
The Newton coefficients are the first entry in each order:
$$ a_0 = f[x_0], $$
$$ a_1 = f[x_0,x_1], $$
$$ a_2 = f[x_0,x_1,x_2], $$
and so on.
Worked example
Use the points
$$ (0,1), \qquad(1,3), \qquad(2,2). $$
The zeroth-order column is
$$ 1,\quad3,\quad2. $$
The first divided differences are
$$ f[x_0,x_1] = \frac{3-1}{1-0} = 2, $$
$$ f[x_1,x_2] = \frac{2-3}{2-1} = -1. $$
The second divided difference is
$$ f[x_0,x_1,x_2] = \frac{-1-2}{2-0} = -\frac{3}{2}. $$
Therefore,
$$ P_2(x) = 1 + 2(x - 0) - \frac{3}{2}(x - 0)(x - 1). $$
Expanding gives
$$ P_2(x) = -\frac{3}{2}x^2 + \frac{7}{2}x + 1, $$
which is exactly the same polynomial produced by the Lagrange form.
At $x=1.5$,
$$ P_2(1.5) = 2.875. $$
Why the construction is incremental
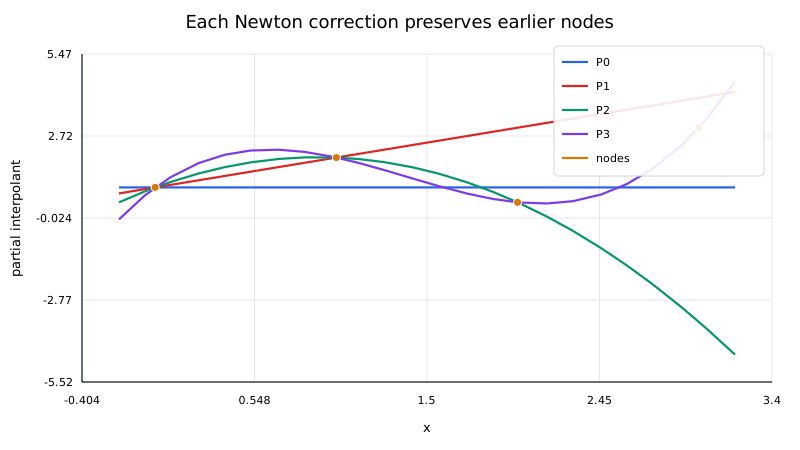
Suppose $P_k(x)$ already interpolates the first $k+1$ nodes. Adding $x_{k+1}$ introduces one new term:
$$ P_{k+1}(x) = P_k(x) + a_{k+1} \prod_{j=0}^{k}(x - x_j). $$
At any earlier node $x_i$ with $i\le k$, the new product contains the factor
$$ x_i - x_i = 0. $$
Therefore the new term vanishes at every old node. The correction can enforce the new data point without disturbing the interpolation conditions that were already satisfied.
Computing the new correction coefficient
The new interpolation condition at $x_{k+1}$ gives
$$ a_{k+1}=\frac{y_{k+1}-P_k(x_{k+1})}{\prod_{j=0}^k(x_{k+1}-x_j)}. $$
The denominator is nonzero because the nodes are distinct. This coefficient is precisely the divided difference $f[x_0,\ldots,x_{k+1}]$. Evaluating $P_k$ in nested form and building the product both take $O(k)$ work, explaining the cost of appending one point.
For example, start with $(0,1),(1,3)$, giving $P_1(x)=1+2x$. The new point $(2,2)$ has discrepancy $2-P_1(2)=2-5=-3$, while the product is $(2-0)(2-1)=2$. Thus $a_2=-3/2$, agreeing with the divided-difference table.
Divided-difference table
For implementation, the coefficients can be computed in place.
Starting from
$$ a_i\leftarrow y_i, $$
update the array order by order:
$$ a_i \leftarrow \frac{a_i-a_{i-1}}{x_i-x_{i-j}} $$
for increasing divided-difference order $j$ and appropriate indices $i$.
More precisely, let $j=1,\ldots,n$ and, for each $j$, update $i=n,n-1,\ldots,j$ in descending order. Each update then reads the two coefficients from the previous order before either has been overwritten. Ascending order would reuse a newly updated value and corrupt the table. After all orders, the array contains $a_i=f[x_0,\ldots,x_i]$.
A full divided-difference table uses $O(n^2)$ storage, but only the coefficient diagonal is needed for evaluation. An in-place implementation can therefore reduce storage to $O(n)$.
The arithmetic cost to build all coefficients is $O(n^2)$.
Nested evaluation
The Newton form should not be evaluated by separately computing every long product.
A nested form analogous to Horner's method is
$$ P_n(x) = a_0 + (x - x_0) \left[a_1 + (x - x_1) \left[a_2 + \cdots + (x - x_{n-1})a_n \right] \right]. $$
This evaluates the polynomial in $O(n)$ operations.
One implementation pattern is:
value = a_n
for k = n-1, ..., 0:
    value = a_k + (x - x_k) * value
Relationship to Lagrange interpolation
For the same $n+1$ distinct nodes and values, Lagrange and Newton interpolation produce the same polynomial.
The difference is the representation:
- Lagrange form emphasizes basis functions with the cardinal property;
- Newton form emphasizes divided differences and incremental construction.
Because the underlying polynomial is identical, both forms have the same approximation error in exact arithmetic.
Error formula
If $f$ has $n+1$ continuous derivatives, then
$$ f(x) - P_n(x) = \frac{f^{(n+1)}(\xi_x)}{(n+1)!} \prod_{i=0}^{n}(x - x_i) $$
for some $\xi_x$ in the interval of interest.
As with Lagrange interpolation, high degree and poor node placement can cause large oscillations.
Equal spacing and finite differences
When nodes are equally spaced, divided differences are closely related to finite-difference tables. This leads to classical Newton forward and backward interpolation formulas.
The general divided-difference form is more flexible because it does not require equal spacing.
Deriving the equally spaced form
If $x_i=x_0+ih$ with $h\ne0$, define forward differences by $\Delta y_i=y_{i+1}-y_i$ and apply the same operation repeatedly. The divided-difference recursion then gives
$$ f[x_i,\ldots,x_{i+k}]=\frac{\Delta^k y_i}{k!h^k}. $$
For the normalized coordinate $s=(x-x_0)/h$, the Newton product is $\prod_{j=0}^{k-1}(x-x_j)=h^k s(s-1)\cdots(s-k+1)$. Substitution cancels the powers of $h$ and yields
$$ P_n(x)=y_0+s\Delta y_0+\frac{s(s-1)}{2!}\Delta^2y_0+\cdots. $$
For the existing three-point example, $h=1$, $\Delta y_0=2$, and $\Delta^2y_0=-3$, so the expression is $1+2s-\tfrac32s(s-1)$. This derives the connection to a finite-difference table; it is not an additional assumption needed by the general Newton form.
Numerical considerations
Newton interpolation avoids solving a Vandermonde system, but it is still a global high-degree polynomial method. Its numerical behavior can deteriorate when:
- the polynomial degree becomes large;
- the nodes are badly scaled;
- the nodes are clustered extremely close together;
- equally spaced nodes produce Runge-type oscillations.
Useful safeguards include:
- shifting and scaling the node coordinates;
- using moderate polynomial degree;
- preferring piecewise splines for large datasets;
- checking interpolation residuals at the nodes;
- comparing against a barycentric Lagrange implementation.
Complexity
For $n+1$ points:
- coefficient construction: $O(n^2)$;
- storage: $O(n)$ for an in-place coefficient array;
- one query: $O(n)$ with nested evaluation;
- adding one new node after existing divided differences are available: $O(n)$ additional work.
This incremental update is one of Newton interpolation's main practical advantages.