Euler's Method
Euler's method is the simplest explicit time-stepping method for an initial value problem (IVP). It is useful both as a practical first approximation and as a way to understand how numerical ODE solvers work.
Consider
$$ u'(t) = f(t,u), \qquad u(t_0) = u_0. $$
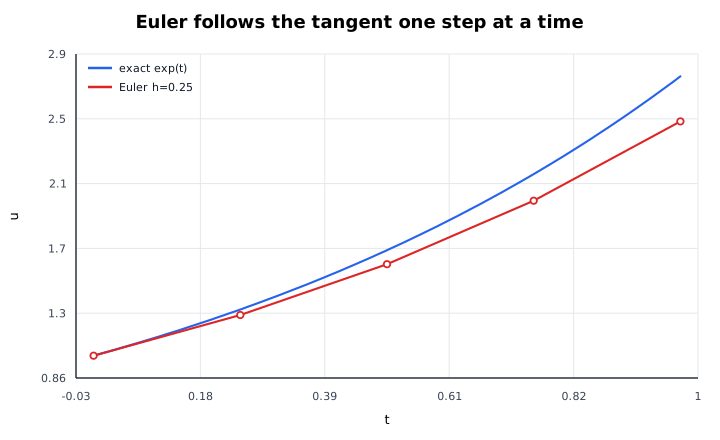
The differential equation gives the slope of the solution curve. Euler's method assumes that this slope remains constant over one short step of length $h$.
Update formula
If $t_n=t_0+nh$ and $u_n$ approximates $u(t_n)$, then
$$ u_{n+1} = u_n + h f(t_n,u_n). $$
This is called forward Euler or explicit Euler because the new value $u_{n+1}$ is computed directly from known quantities at step $n$.
Geometrically:
- evaluate the slope $f(t_n,u_n)$,
- follow the tangent line for a horizontal distance $h$,
- use the endpoint as the next numerical value.
Derivation from Taylor expansion
Expand the exact solution about $t_n$:
$$ u(t_n + h) = u(t_n) + h u'(t_n) + \frac{h^2}{2}u''(\xi_n), $$
for some $\xi_n\in(t_n,t_n+h)$. Since $u'(t_n)=f(t_n,u(t_n))$,
$$ u(t_n + h) = u(t_n) + h f(t_n,u(t_n)) + O(h^2). $$
Dropping the $O(h^2)$ term gives Euler's update.
This immediately explains the method's error:
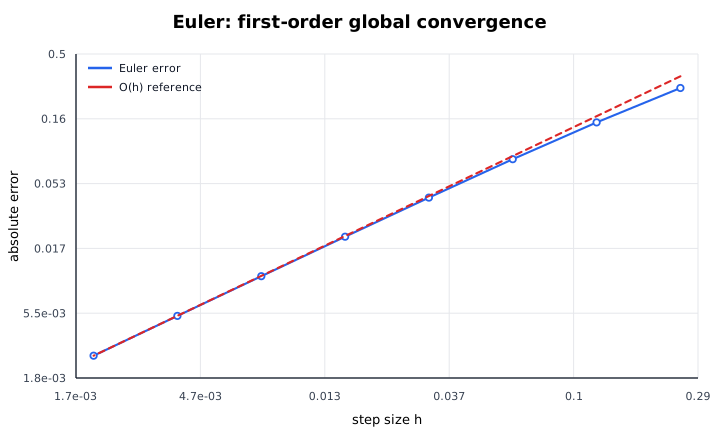
- local truncation error: $O(h^2)$ per step,
- global error: $O(h)$ over a fixed time interval.
So halving the step size should roughly halve the total error once the asymptotic regime is reached.
How local error accumulates
The $O(h^2)$ local error refers to one step starting from the exact value. In a computed trajectory, each new step also propagates earlier errors. If $f$ is Lipschitz in $u$ with constant $L$ and $|u''|\leq M$, the global error $e_n=|u(t_n)-u_n|$ satisfies
$$ e_{n+1}\leq(1+hL)e_n+\frac{M}{2}h^2. $$
Starting with $e_0=0$ and summing the geometric series gives, for $L>0$,
$$ e_n\leq\frac{M}{2L}h\bigl((1+hL)^n-1\bigr)\leq\frac{M}{2L}h(e^{L(t_n-t_0)}-1). $$
On a fixed time interval the factor multiplying $h$ is bounded, giving first-order global accuracy. If $L=0$, the corresponding bound is $M(t_n-t_0)h/2$. This argument also explains why smoothness and controlled error propagation are needed; simply counting steps does not establish convergence for every differential equation.
For $u'=u$, the recurrence is $u_n=(1+h)^n u_0$ on a uniform grid. At fixed $T=nh$, $n\log(1+h)=T-Th/2+O(h^2)$, so the numerical growth differs from $e^T$ by a first-order term. When comparing vector ODEs, compute every component of $f(t_n,\mathbf u_n)$ from the same old state before updating the state.
Worked example
Solve approximately
$$ u' = u, \qquad u(0) = 1 $$
up to $t=0.1$ using $h=0.05$.
The exact solution is $u(t)=e^t$.
First step:
$$ u_1 = u_0 + h u_0 = 1 + 0.05(1) = 1.05. $$
Second step:
$$ u_2 = u_1 + h u_1 = 1.05 + 0.05(1.05) = 1.1025. $$
Thus
$$ u(0.1)\approx 1.1025. $$
The exact value is
$$ e^{0.1}\approx 1.105170918. $$
The error is about $2.67\times 10^{-3}$.
Algorithm
For a scalar ODE:
t = t0
u = u0

while t < tf:
    h_n = min(h, tf - t)    # shorten the last step to land on tf
    u = u + h_n*f(t, u)
    t = t + h_n
For a system
$$ \mathbf{u}' = \mathbf{f}(t,\mathbf{u}), $$
the same formula applies componentwise:
$$ \mathbf{u}_{n+1} = \mathbf{u}_n + h\mathbf{f}(t_n,\mathbf{u}_n). $$
Repository implementation
euler_method takes a final time t_end and a nominal step h. When (t_end - t0)/h is not an integer, the last step is shortened so that the returned grid ends exactly at t_end; all earlier steps have length h. The returned array has shape (n + 1,) for a scalar ODE (one component) and (n + 1, d) for a system with d components.
Step size and stability
Accuracy is not the only reason to choose $h$ carefully. A step can be small enough to look reasonable but still be unstable.
For the test equation
$$ u' = \lambda u, $$
Euler gives
$$ u_{n+1} = (1 + h\lambda)u_n. $$
If $\lambda<0$, the exact solution decays. The numerical solution decays only if
$$ |1 + h\lambda|<1. $$
For real negative $\lambda$, this requires
$$ 0<h< \frac{2}{|\lambda|}. $$
Stability does not imply that the numerical decay has the same shape as the exact decay. For $\lambda<0$ and $1<h|\lambda|<2$, the factor $1+h\lambda$ is negative with magnitude below one: the numerical values alternate in sign while decreasing in magnitude. For example, $\lambda=-1$ and $h=1.5$ give factor $-0.5$, while the exact positive initial solution remains positive. Preserving nonnegative decay requires the stricter condition $0<h\leq1/|\lambda|$ in this scalar example.
This restriction is severe for stiff problems, where some modes decay much faster than others. Explicit Euler may then require extremely small steps even when the solution itself changes slowly.
When Euler's method is useful
Euler's method is valuable when:
- learning the mechanics of time stepping,
- obtaining a quick rough approximation,
- building or debugging a more advanced solver,
- exploring a model before investing in a higher-order method.
It is usually not the best production method when high accuracy or stiffness matters.
Advantages
- Very simple to derive and implement.
- Requires only one evaluation of $f$ per step.
- Extends directly to systems of ODEs.
- Makes error, stability, and time-stepping ideas easy to visualize.
Limitations
- Only first-order accurate globally.
- Can accumulate substantial error over many steps.
- Has a small stability region.
- Performs poorly on stiff problems.
- A fixed step size can waste work in smooth regions and miss rapid changes elsewhere.