Ordinary Differential Equations
An ordinary differential equation (ODE) relates an unknown function of one independent variable to one or more of its derivatives. ODEs are the natural language of dynamical systems: they describe how a state changes when its instantaneous rate of change is known.
A general $n$th-order ODE can be written as
$$ F\left(t, y, y', \ldots, y^{(n)} \right) = 0. $$
The word ordinary means that derivatives are taken with respect to a single independent variable. If several independent variables appear, the corresponding equation is a partial differential equation.
From a model to a trajectory
A common first-order form is
$$ y'(t) = f(t,y(t)), \qquad y(t_0) = y_0. $$
At every point $(t,y)$, the function $f$ specifies the slope of a possible solution curve. The initial condition chooses one trajectory from that slope field.
Autonomous problems have the form
$$ y' = f(y), $$
so the direction of motion depends only on the current state.
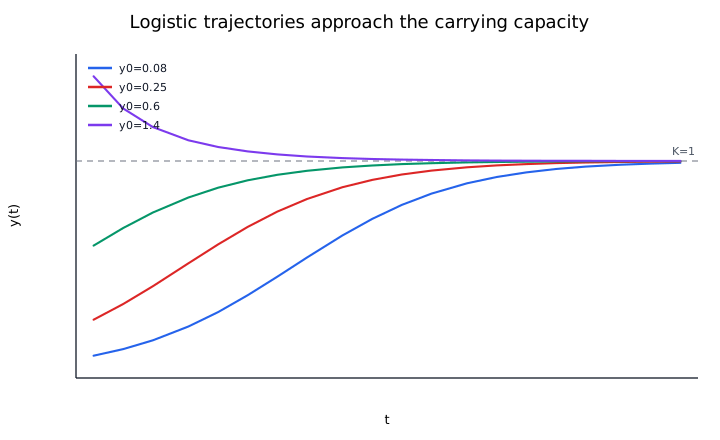
For example, the logistic equation
$$ y' = r y\left(1 - \frac{y}{K}\right) $$
with $r>0$ and $K>0$ has equilibria at $y=0$ and $y=K$. When $0<y<K$, the derivative is positive; when $y>K$, it is negative. This qualitative information already reveals the long-term behavior without solving the equation explicitly.
Initial value problems and boundary value problems
An initial value problem (IVP) specifies all required conditions at one point. For a second-order ODE,
$$ y'' = g(t,y,y'), $$
a typical IVP is
$$ y(t_0) = y_0, \qquad y'(t_0) = v_0. $$
A boundary value problem (BVP) specifies conditions at different locations, for example
$$ y'' + y = 0, \qquad y(0) = 0, \qquad y(1) = 1. $$
IVPs are naturally advanced forward or backward in the independent variable. BVPs usually require different numerical ideas such as shooting or finite differences.
Classification
Order
The order is the highest derivative present.
- $y'=f(t,y)$ is first order.
- $y''+3y'+2y=0$ is second order.
- $y^{(4)}+y=0$ is fourth order.
Linear and nonlinear ODEs
A linear $n$th-order ODE has the form
$$ a_n(t)y^{(n)} + \cdots + a_1(t)y' + a_0(t)y = g(t). $$
The unknown function and its derivatives appear only linearly.
Examples:
$$ y' + 2y = \sin t $$
is linear, while
$$ y' = y^2 - t $$
and
$$ y'' + \sin y = 0 $$
are nonlinear.
Homogeneous and nonhomogeneous linear equations
A linear equation is homogeneous when $g(t)=0$. Otherwise it is nonhomogeneous.
Converting higher-order equations to first-order systems
Numerical solvers are usually written for first-order systems. A higher-order ODE can be rewritten in that form when it can be solved locally for its highest derivative. An implicit or singular equation may instead require a differential-algebraic formulation.
For
$$ y'' + c y' + k y = 0, $$
define
$$ u_1 = y, \qquad u_2 = y'. $$
Then
$$ u_1' = u_2, $$
$$ u_2' = -k u_1 - c u_2. $$
So the second-order scalar problem becomes
$$ \mathbf{u}' = \mathbf{f}(t,\mathbf{u}). $$
For order $n$, define $u_1=y,u_2=y',\ldots,u_n=y^{(n-1)}$. Then $u_j'=u_{j+1}$ for $j<n$, and the final equation comes from the isolated highest derivative. The initial values of all $n$ components must also be supplied.
Existence and uniqueness
For
$$ y' = f(t,y), \qquad y(t_0) = y_0, $$
a standard local result is the Picard--Lindelof theorem. Roughly, if:
- $f$ is continuous near $(t_0,y_0)$, and
- $f$ is Lipschitz continuous in $y$,
then the IVP has a unique local solution.
A Lipschitz condition in $y$ means there is a constant $L$ such that
$$ |f(t,y_1) - f(t,y_2)| \le L|y_1 - y_2|. $$
This condition prevents nearby solution curves from splitting unpredictably.
Local does not mean global
Continuity and a local Lipschitz condition establish existence and uniqueness only on some neighborhood of the initial point. A solution can leave the domain or become unbounded in finite time. For example, $y'=y^2$, $y(0)=1$ has the unique solution $y(t)=1/(1-t)$, which cannot be extended as a finite-valued solution through $t=1$.
Continuity alone does not guarantee uniqueness. The problem $y'=2\sqrt{|y|}$, $y(0)=0$ admits the zero solution and solutions that remain zero until a chosen time $a\geq0$ and then follow $(t-a)^2$. The right-hand side is continuous but not locally Lipschitz at zero. These examples show why a numerical trajectory must be interpreted within the mathematical domain of the IVP.
Analytical versus numerical solutions
Some ODEs have closed-form solutions. Many important nonlinear systems do not.
For example,
$$ y' = ay $$
has the exact solution
$$ y(t) = y_0e^{a(t-t_0)}. $$
But once $f$ becomes nonlinear, coupled, discontinuous, or expensive, numerical integration is often the practical route.
Common explicit methods include:
- Euler's method,
- Heun's method,
- Runge–Kutta methods.
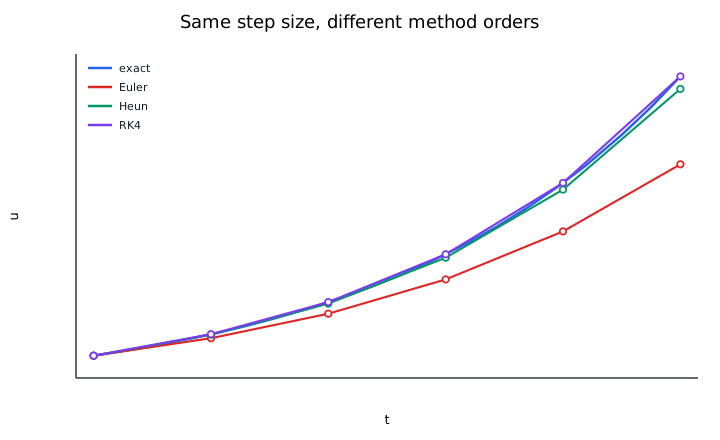
Their accuracy can differ dramatically at the same step size.
Local and global error
A one-step method advances by
$$ u_{n+1} = \Phi_h(t_n,u_n). $$
Two distinct errors are useful:
- local truncation error: the error produced in one step when starting from the exact solution,
- global error: the accumulated difference after many steps.
A method of global order $p$ typically satisfies
$$ \max_n |u(t_n) - u_n| = O(h^p) $$
on a fixed interval as $h\to0$.
Euler has order $1$, Heun order $2$, and classical RK4 order $4$.
Error conventions and convergence conditions
These notes call the unscaled one-step defect the local truncation error: starting from the exact value, a method of order $p$ has defect $O(h^{p+1})$. Some texts divide that defect by $h$ and call the resulting $O(h^p)$ quantity the local truncation error. The conventions describe the same method but attach different exponents to the term “local.”
A stable one-step propagation bound has the form
$$ e_{n+1}\leq(1+Ch)e_n+Kh^{p+1}. $$
Over a fixed interval, summing this recurrence gives $e_n=O(h^p)$ when the initial error is controlled. Thus consistency, smoothness, and stability together justify the global orders listed above. Reducing $h$ cannot compensate for an incorrect model, uncertain initial conditions, or a solution singularity.
For a scaled local-error estimate $E=\max_i |e_i|/(\mathrm{atol}_i+\mathrm{rtol}|u_i|)$, a controller typically accepts a trial step when $E\leq1$. The absolute tolerance controls components near zero, while relative tolerance controls components with appreciable magnitude. A rejected trial step is recomputed with a smaller step rather than included in the trajectory.
Stability and stiffness
Accuracy alone does not guarantee a good numerical solution.
For the test equation
$$ y' = \lambda y, $$
a numerical method produces
$$ y_{n+1} = R(h\lambda)y_n, $$
where $R$ is the method's stability function. For $\operatorname{Re}\lambda<0$ the exact solution decays, so the numerical solution should satisfy $|R(h\lambda)|\le1$ as well.
For example, forward Euler has $R(z)=1+z$, which restricts $h$ to $|1+h\lambda|\le1$ (for real $\lambda<0$: $h\le2/|\lambda|$). Backward Euler has $R(z)=1/(1-z)$ and satisfies $|R(z)|\le1$ for every $z$ with $\operatorname{Re}z\le0$, so it is stable for any $h$ on decaying modes.
A problem is called stiff when rapidly decaying modes force explicit methods to use very small steps for stability even though the physically interesting solution evolves on a much slower time scale.
In stiff regimes, implicit methods such as backward Euler, BDF schemes, or implicit Runge–Kutta methods are usually preferred.
Adaptive step sizes
Modern ODE solvers rarely use a single fixed $h$ everywhere. Instead they estimate local error and adapt the step size:
- reduce $h$ when the solution changes rapidly,
- increase $h$ when the solution is smooth.
Embedded Runge–Kutta pairs, such as RK45, obtain two approximations of different orders from related stage evaluations and use their difference as an error estimate.
Deriving a step-size controller
Suppose the scaled error estimate behaves like $E(h)\approx Ch^q$ over nearby trial steps. To make the next estimate near one, solve $1\approx E(h)(h_{\mathrm{new}}/h)^q$, giving
$$ h_{\mathrm{new}}=\eta h\,E(h)^{-1/q},\qquad 0<\eta<1. $$
The factor $\eta$ leaves a margin because $C$ is only estimated. Practical controllers also limit how quickly the step can grow or shrink. The exponent comes from the error estimate, not just the order of the solution that is retained. For a fourth/fifth-order embedded pair, their difference is typically $O(h^5)$, so a basic controller uses $q=5$. An estimate of zero requires a capped growth rule rather than division by zero.
Important model examples
Exponential growth and decay
$$ y' = ay. $$
The sign of $a$ determines growth or decay.
Logistic growth
$$ P' = rP\left(1 - \frac{P}{K}\right). $$
The parameter $K$ is the carrying capacity.
Harmonic oscillator
$$ x'' + \omega^2x = 0. $$
As a first-order system:
$$ x' = v, \qquad v' = -\omega^2x. $$
Damped oscillator
$$ x'' + 2\zeta\omega x' + \omega^2x = 0. $$
The damping ratio $\zeta$ controls whether the motion is underdamped, critically damped, or overdamped.
A practical workflow
When solving an ODE numerically:
- identify whether the problem is an IVP or BVP,
- rewrite higher-order equations as a first-order system,
- inspect scales, smoothness, and possible stiffness,
- choose a suitable method and tolerance,
- verify convergence by tightening the step or tolerance,
- compare against invariants, known limits, or exact solutions when available,
- interpret the numerical result in the context of the model.