Runge--Kutta Methods
Runge--Kutta methods advance an ODE solution using several carefully chosen slope evaluations inside each step. They achieve higher-order accuracy without requiring explicit derivatives of $f$ beyond the first derivative already present in the ODE.
Consider
$$ u'(t) = f(t,u), \qquad u(t_0) = u_0. $$
The best-known member of the family is the classical fourth-order Runge--Kutta method, usually called RK4.
Classical RK4
Given $(t_n,u_n)$ and step size $h$,
$$ k_1 = f(t_n,u_n), $$
$$ k_2 = f\left(t_n + \frac{h}{2}, u_n + \frac{h}{2}k_1 \right), $$
$$ k_3 = f\left(t_n + \frac{h}{2}, u_n + \frac{h}{2}k_2 \right), $$
$$ k_4 = f(t_n + h,u_n + h k_3). $$
Then
$$ u_{n+1} = u_n + \frac{h}{6} \left(k_1 + 2k_2 + 2k_3 + k_4 \right). $$
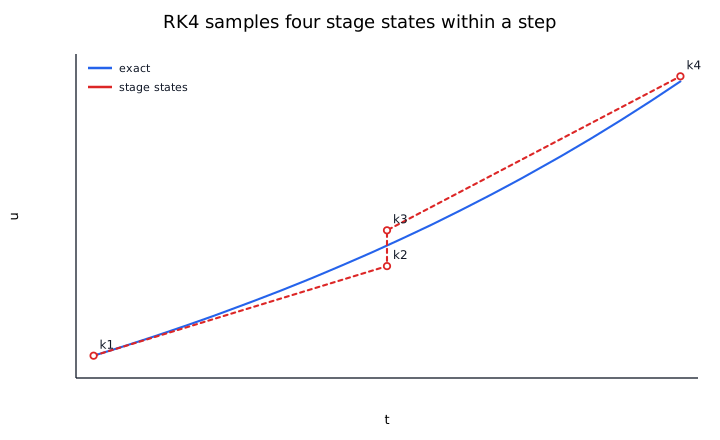
The four stages sample the vector field at the beginning, twice near the middle, and at the end of the step.
Why RK4 Is Fourth Order
The exact solution has a Taylor expansion containing derivatives such as $u''$, $u'''$, and $u^{(4)}$. Those derivatives can be expressed using derivatives of $f$, but computing them explicitly is inconvenient.
Runge--Kutta methods instead choose stage locations and weights so that the expansion of the numerical update matches the Taylor expansion through a desired order.
For RK4:
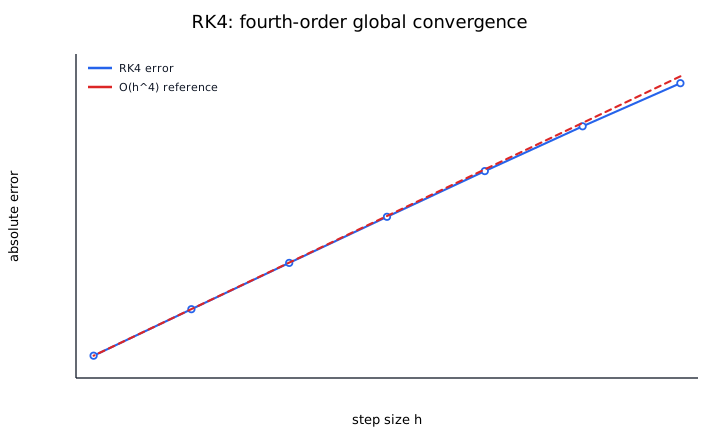
- local truncation error is $O(h^5)$,
- global error is $O(h^4)$.
Therefore, halving $h$ reduces the global error by roughly a factor of $16$ in the asymptotic regime.
Worked Example
For
$$ u' = u, \qquad u(0) = 1, $$
with $h=0.1$:
$$ k_1 = 1, $$
$$ k_2 = 1 + 0.05k_1 = 1.05, $$
$$ k_3 = 1 + 0.05k_2 = 1.0525, $$
$$ k_4 = 1 + 0.1k_3 = 1.10525. $$
Thus
$$ u_1 = 1 + \frac{0.1}{6} \left(1 + 2(1.05) + 2(1.0525) + 1.10525 \right), $$
which gives
$$ u_1\approx1.105170833. $$
The exact solution is
$$ e^{0.1}\approx1.105170186. $$
The error after a single step is already below $10^{-6}$.
Butcher Tableau
A Runge--Kutta method can be summarized by a Butcher tableau. For RK4:
$$ \begin{array}{c|cccc} 0 \\ \frac12 & \frac12 \\ \frac12 & 0 & \frac12 \\ 1 & 0 & 0 & 1 \\ \hline & \frac16 & \frac13 & \frac13 & \frac16 \end{array} $$
The entries specify:
- where each stage is evaluated,
- how previous stages construct the stage state,
- how the final stages are combined.
General Explicit Runge--Kutta Form
For an $s$-stage explicit method,
$$ k_i = f\left(t_n + c_i h, u_n + h\sum_{j=1}^{i-1}a_{ij}k_j \right), $$
and
$$ u_{n+1} = u_n + h\sum_{i=1}^{s}b_i k_i. $$
Different choices of the coefficients produce different methods and orders.
Adaptive Runge--Kutta Methods
Fixed-step RK4 is simple, but modern solvers often use embedded pairs, such as RK45.
An embedded pair computes two approximations of different orders using mostly the same stage evaluations. Their difference estimates the local error.
A controller then changes $h$:
- decrease $h$ when estimated error is too large,
- increase $h$ when the solution is smooth.
This can reduce work dramatically when a problem alternates between easy and difficult regions.
Stability
For
$$ u' = \lambda u, $$
RK4 has stability polynomial
$$ R(z) = 1 + z + \frac{z^2}{2} + \frac{z^3}{6} + \frac{z^4}{24}, \qquad z = h\lambda. $$
The method is stable where
$$ |R(z)|\le1. $$
RK4 has a useful explicit stability region but is not A-stable. Strongly stiff systems may still demand impractically small steps.
RK4 Versus Euler and Heun
| Method | Evaluations of $f$ per step | Global order |
|---|---|---|
| Euler | 1 | 1 |
| Heun | 2 | 2 |
| RK4 | 4 | 4 |
Higher order does not automatically mean lower total cost. The best method depends on:
- desired accuracy,
- cost of evaluating $f$,
- smoothness,
- stiffness,
- whether adaptive time stepping is available.
Systems of ODEs
RK4 applies directly to
$$ \mathbf{u}' = \mathbf{f}(t,\mathbf{u}). $$
Each $k_i$ becomes a vector. This makes RK methods convenient for mechanics, circuits, chemical kinetics, population models, and other coupled systems.
Advantages
- High accuracy for smooth non-stiff IVPs.
- No need to compute higher derivatives.
- Straightforward extension to systems.
- Well understood and easy to verify on benchmark problems.
Limitations
- Four function evaluations per RK4 step.
- Fixed-step RK4 has no built-in error estimator.
- Explicit Runge--Kutta methods can be inefficient on stiff equations.
- Very long integrations may require methods that better preserve invariants or geometric structure.